China RMB Settlement and Exporter Credit

Driss EFFINA, PhD Independent Researcher, Global Strategy Files Decoded, China series, 24 October 2026.
The missing link is a dated cash record
Does greater use of RMB shift financing from foreign buyers to Chinese exporters? The public evidence assembled here cannot identify that causal effect. It shows substantial growth in covered RMB payments, selected changes in one issuer’s receivables, and important differences between statistical perimeters. It does not jointly observe the currency of an export invoice, the buyer’s loan, the agreed due date, actual collection and the exporter’s usable credit. Missing identification is an empirical finding about the available records, not an estimate that the economy-wide effect equals zero.
A separate accounting result is exact. Preserve a USD claim, payment date, contemporaneous conversion rule and fees, and switch only the money delivered at settlement from USD to RMB. The exporter’s CNY cash path is unchanged. Additional financing in the experiments that follow requires some further change: a later receipt, a changed nominal claim, a conversion funding gap or a different financial instrument. The zero comparison prevents a currency label from silently becoming an assumed credit shock.
The original contribution combines an auditable public-data perimeter study with a daily exporter treasury experiment. SAFE supplies a complete 2010-2025 annual window in the retained workbook; selected PBOC vintages, CIPS business statistics and Midea’s consolidated accounts supply complementary, differently scoped evidence. The model then follows twelve explicitly synthetic invoices through production, payment and debt repayment. It calculates required capacity, financing charges and terminal cash separately, and compares a finite-grid treasury design with explicit counterexamples. (SAFE series) (CIPSH) (Midea Notes 27/29)
RMB use grew within a specified perimeter
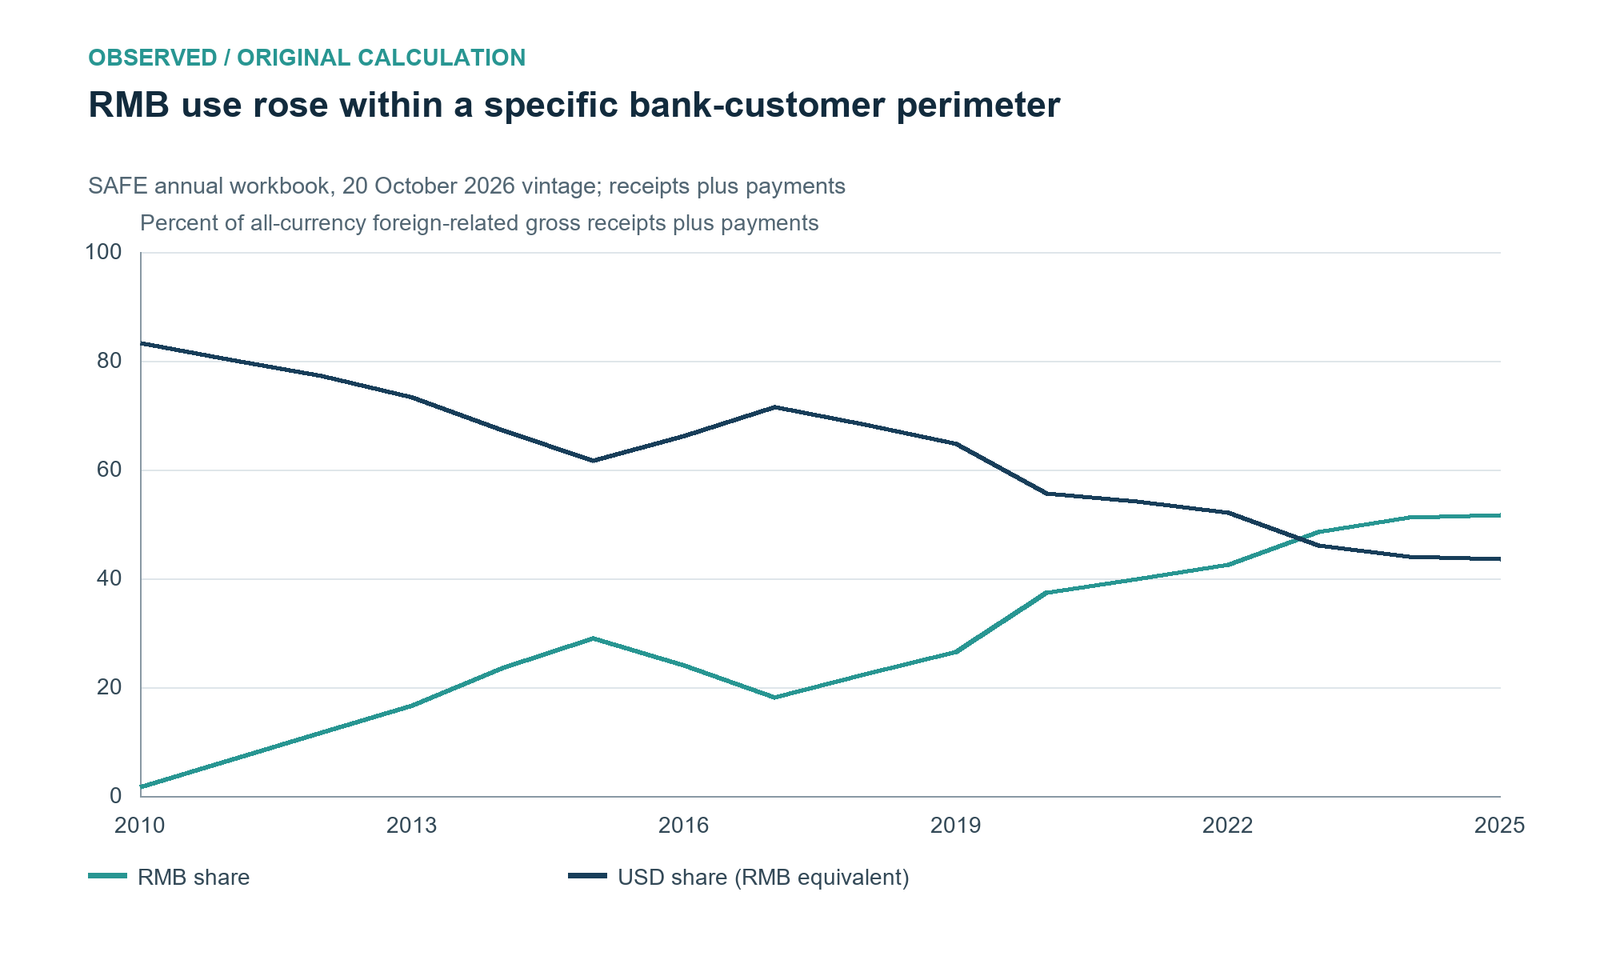
The SAFE workbook updated on 20 October 2026 permits a consistent calculation from its directly reported currency margins. RMB receipts plus payments accounted for 1.690% of covered gross customer foreign-related flows in 2010 and 51.635% in 2025, an endpoint increase of 49.945 percentage points. The intervening path is not monotonic. These calculations retain the workbook’s current historical vintage rather than stitching releases with different revisions. (SAFE series)
Declare the complete synthetic invoice book
The model is a dated cash experiment, with every economic input assumed. It follows twelve reference invoices worth CNY 1 million each, shipped thirty days apart. Production costs CNY 0.8 million per invoice and is paid twenty days before shipment. The ordinary contractual payment is sixty days after shipment. Opening unrestricted exporter cash is CNY 0.5 million; drawn domestic borrowing costs 4.8% per year, capitalized daily on an actual/365 basis. These values do not describe a representative Chinese exporter.
The exchange reference is 7 CNY per USD. A fixed-RMB invoice pays its fixed CNY face, while a USD invoice has reference face equal to CNY 1 million divided by seven and converts at the payment-date spot rate. Main timing contrasts hold that rate at seven and retain all receipts: rho, the receipt-retention fraction, equals one. Separate FX and loss sensitivities change those assumptions explicitly. No delay is inferred from an RMB label, and no scenario probability is inferred from a public payment share.
The constructed calendar begins with shipment day zero on 1 January 2026. The first production payment is day -20, or 12 December 2025. The common analysis window runs from day -20 through day 600 and contains 620 daily interest intervals. Later calendar rows are hypothetical scheduled dates. They are not reported future outcomes, forecasts or an annualization of the actual 2026 partials.
Day-end operating cash flows net on the same date, interest is charged on opening debt, and retained operating margins repay borrowing. Cash earns no deposit return. There are no dividends, unrelated businesses, taxes, new capital expenditures or residual inventory value. Jobs, production and invoice quantities do not respond to finance constraints within the experiment. This fixed-book convention isolates the cash mechanism but does not predict a firm’s chosen order volume or contractual equilibrium.
The following section declares the instruments, risk states and treasury design before numerical findings. All remain scenarios. Midea’s generally sixty-day contractual disclosure supplies context, not validation or calibration of the synthetic book. Applying the model to a real exporter would require its cost dates, unrestricted cash and genuinely usable facilities, together with invoice-specific currencies, terms, collections and recourse provisions. The normalization makes those requirements visible and permits independent reconstruction of every calculation.
Table 5. Core fixed-book assumptions
| Input | Declared value |
|---|---|
| Invoices and spacing | 12 times CNY 1 million; shipment every 30 days. |
| Production | CNY 0.8 million paid 20 days before shipment. |
| Ordinary due date | 60 days after shipment. |
| Cash and drawn rate | CNY 0.5 million; 4.8% annual, daily actual/365. |
| Conversion and retention | 7 CNY/USD reference; central rho=1 (no loss). |
| Common window | Day -20 through 600; 620 interest intervals. |
Every value is an illustrative assumption. None is a representative-exporter estimate.
Assumed instruments, risks and treasury choices
The central timing states add zero, thirty or ninety days to ordinary collection, keeping quantities and production dates fixed. A separate threshold grid adds zero through 180 integer days; the delay-rate sensitivity uses zero through 120 additional days and annual rates from zero to 9.6%. FX states run from 5.6 to 8.4 CNY per USD. These are sensitivity domains, without an estimated distribution or confidence interpretation.
The mechanical buyer funding gate assumes USD capacity of one million divided by seven, or RMB capacity of one million, at the due date. A conversion gap is filled by new USD 1,000 per day or CNY 7,000 per day. The gate compares fixed-RMB and fixed-USD claims in both directions. It omits buyer profits, local-currency revenues and loan interest, so it is a funding rule rather than an estimated repayment response or bilateral welfare model.
Full prepayment arrives on the production-cost date. An assumed performing bank can pay on the ordinary due date despite buyer delay; a separate sight case pays at shipment after compliant documents. Their bank fees and failure probabilities are not calibrated. Factoring uses a nonrecourse fixed-RMB claim, a central 90% advance at shipment and a 1% fee on full face, deducted immediately. Ten percent remains for buyer collection; factoring is not combined with prepayment. The ideal full hedge fixes the reference conversion and charges 0.2% of face at shipment, with no collateral calls, basis, roll or late-payment closeout risk.
Loss is separate from delay. Receipt retention rho equals one minus a specified haircut; the zero, one, three and five percent haircut grid is not estimated default risk. A fair premium is solved by seventy bisection steps to match baseline terminal net cash only. It contains no risk-aversion, enforcement, tax or equilibrium bargaining estimate.
Treasury design chooses cash and a committed line before a common delay state. The main grid runs each from zero to CNY 3 million in CNY 50,000 steps, giving 3,721 designs. Assumed state weights are 0.6, 0.3 and 0.1. Buffer carry is 3% annually, commitment 0.8%, both for 620/365 years. The objective adds expected drawn interest and a central weight of 0.25 on 90% conditional value at risk of peak uncovered capacity. Robust comparisons require coverage of all three states; their expected-interest cost still uses the same weights. An expanded frontier allows cash and line caps up to CNY 6 million. Coverage refers only to this finite state set.
For buffer B and line L, uncovered capacity is max(required peak debt minus L,0). The design objective adds expected drawn interest, (620/365) times (0.03B+0.008L), and lambda times CVaR90 of this uncovered peak. CVaR is the worst 10% probability-tail average; lambda is an assumed preference, not measured damage. Required uncapped borrowing is diagnostic: if the line is insufficient, the book is not funded. The finite robust comparator covers only the declared states. The price root equates final net cash, with no equilibrium or risk-aversion claim.
Later collection raises the required credit peak
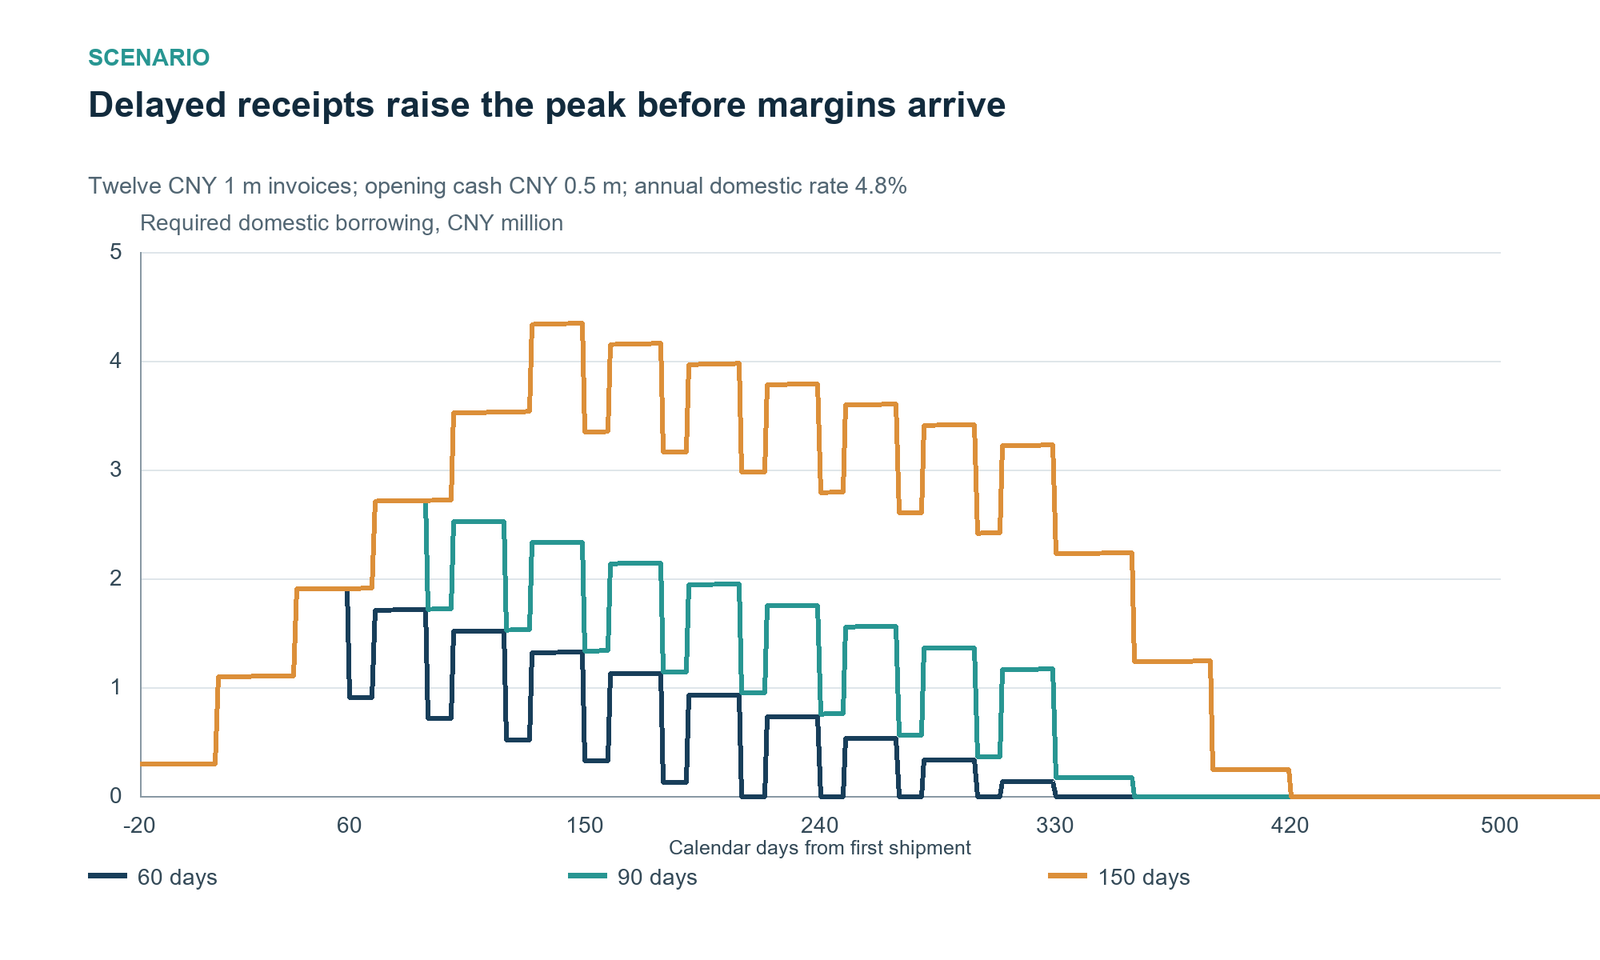
At ordinary sixty-day collection, the synthetic book requires peak borrowing of CNY 1.910305 million and incurs CNY 35,944.84 of interest. Add thirty days to collection while preserving the book, reference exchange rate, full receipt retention and other inputs: peak credit becomes CNY 2.719858 million and interest CNY 70,820.60. Figure 7 traces those dated deficits instead of replacing them with an annual receivables ratio.
With ninety additional days, collection is 150 days after shipment. Peak required borrowing reaches CNY 4.348575 million and interest CNY 144,887.48. Relative to ordinary collection, the increments are CNY 2.438269 million in peak capacity and CNY 108,942.64 in financing charge. They describe the assumed timing change. They are not an estimated response of Chinese exporters to invoicing or settlement in RMB.
The operating margin does not disappear. Twelve million of face receipts and CNY 9.6 million of production costs still leave CNY 2.4 million before financing. Retained margins arrive later and repay the accumulated line later, generating the larger interest area. This is why peak principal and interest must be reported separately rather than added as an economic loss.
The uncapped curve is a diagnostic demand for capacity. A bank has not promised that capacity simply because the curve is calculated. With a smaller usable line, the fixed production plan needs a buffer or another financing arrangement. The same shortfall could also lead to smaller shipments or altered supplier terms, responses deliberately held outside this accounting experiment.
The zero and the counterexamples are substantive
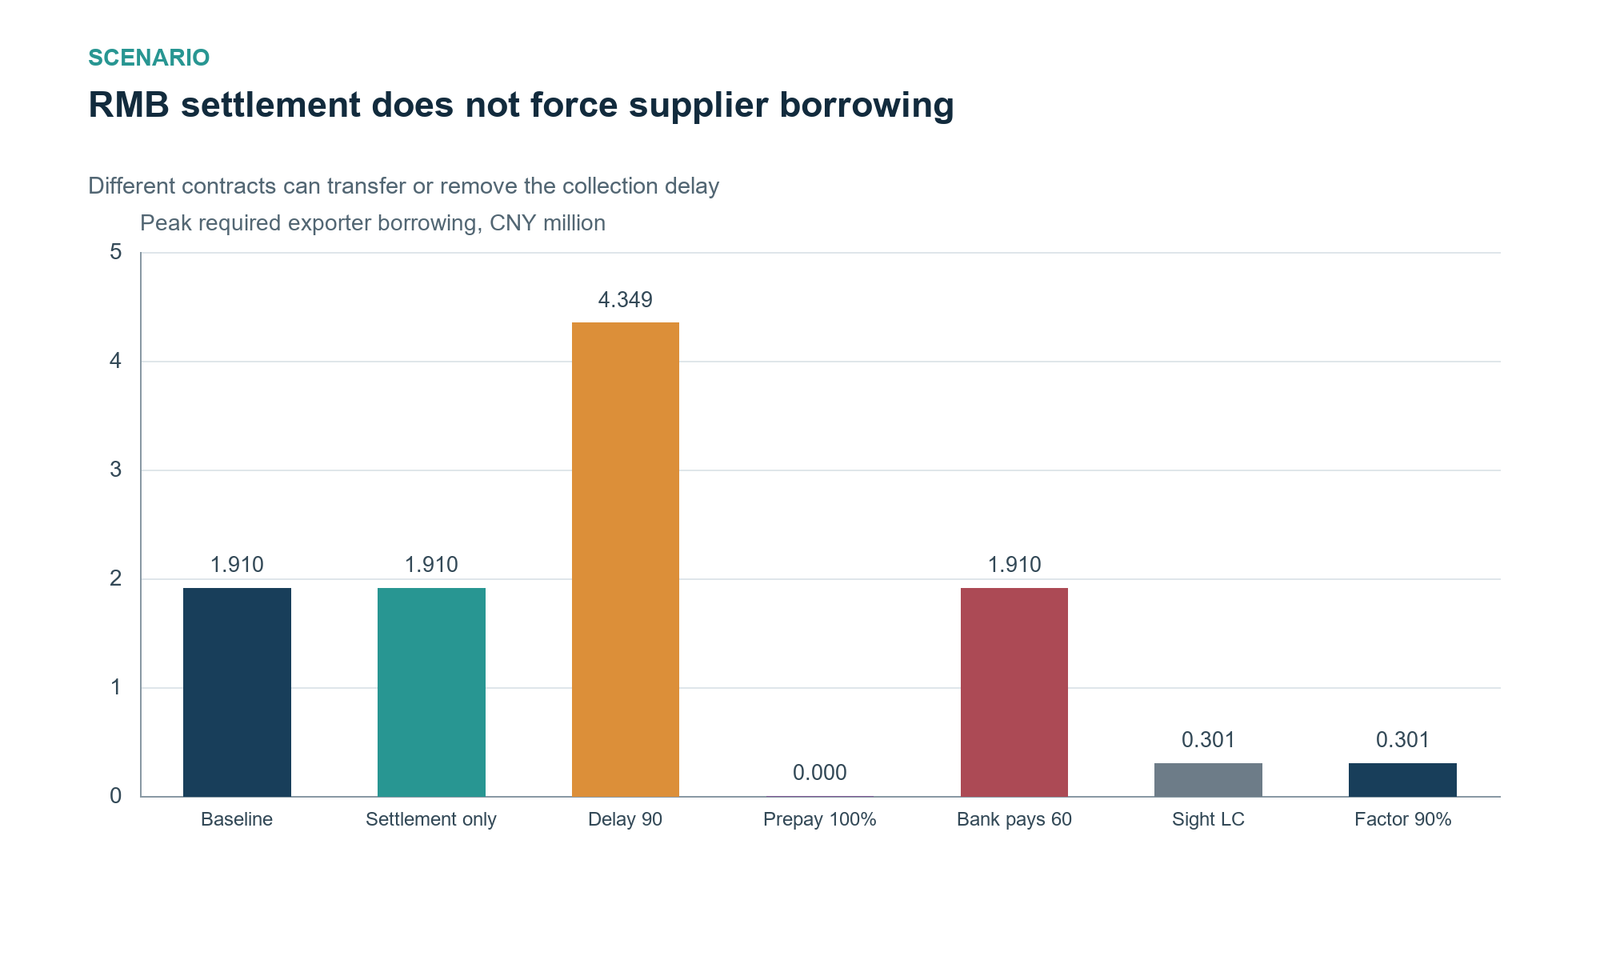
The settlement-only comparison changes a USD invoice’s delivered payment currency to RMB at the same contemporaneous spot conversion, date and fee. It leaves the entire CNY cash path unchanged: peak debt remains CNY 1.910305 million, interest CNY 35,944.84 and terminal net cash CNY 2.864055 million. The exact identity holds more generally for the same specified conversion path. Fixed-RMB invoicing also matches at the constant reference rate, but defines a different claim when exchange rates move.
Figure 8 includes other disconfirming arrangements. Full prepayment on the production-cost date eliminates exporter borrowing in this book. An assumed bank honoring ordinary sixty-day payment despite buyer delay restores baseline timing. A sight bank payment at shipment leaves CNY 0.300750 million of peak production-stage borrowing because costs precede shipment. Neither a bank guarantee nor a payment label automatically finances that earlier period.
A sufficiently large unrestricted opening buffer also eliminates drawn debt in its particular comparison. Matched RMB buyer capacity removes the specified conversion funding gap, without proving that operational delays or disputes vanish. These cases make a necessary exporter-credit shift untenable as a universal proposition.
Counterexamples have conditions and costs. Prepayment moves financing to the buyer; bank performance and documents are assumed; cash has an opportunity cost; factoring charges fees and transfers exposure. The results reject the claim that settlement currency alone must lengthen supplier credit. They do not establish that one instrument is free, universally available or welfare superior.
A late premium can restore value without liquidity
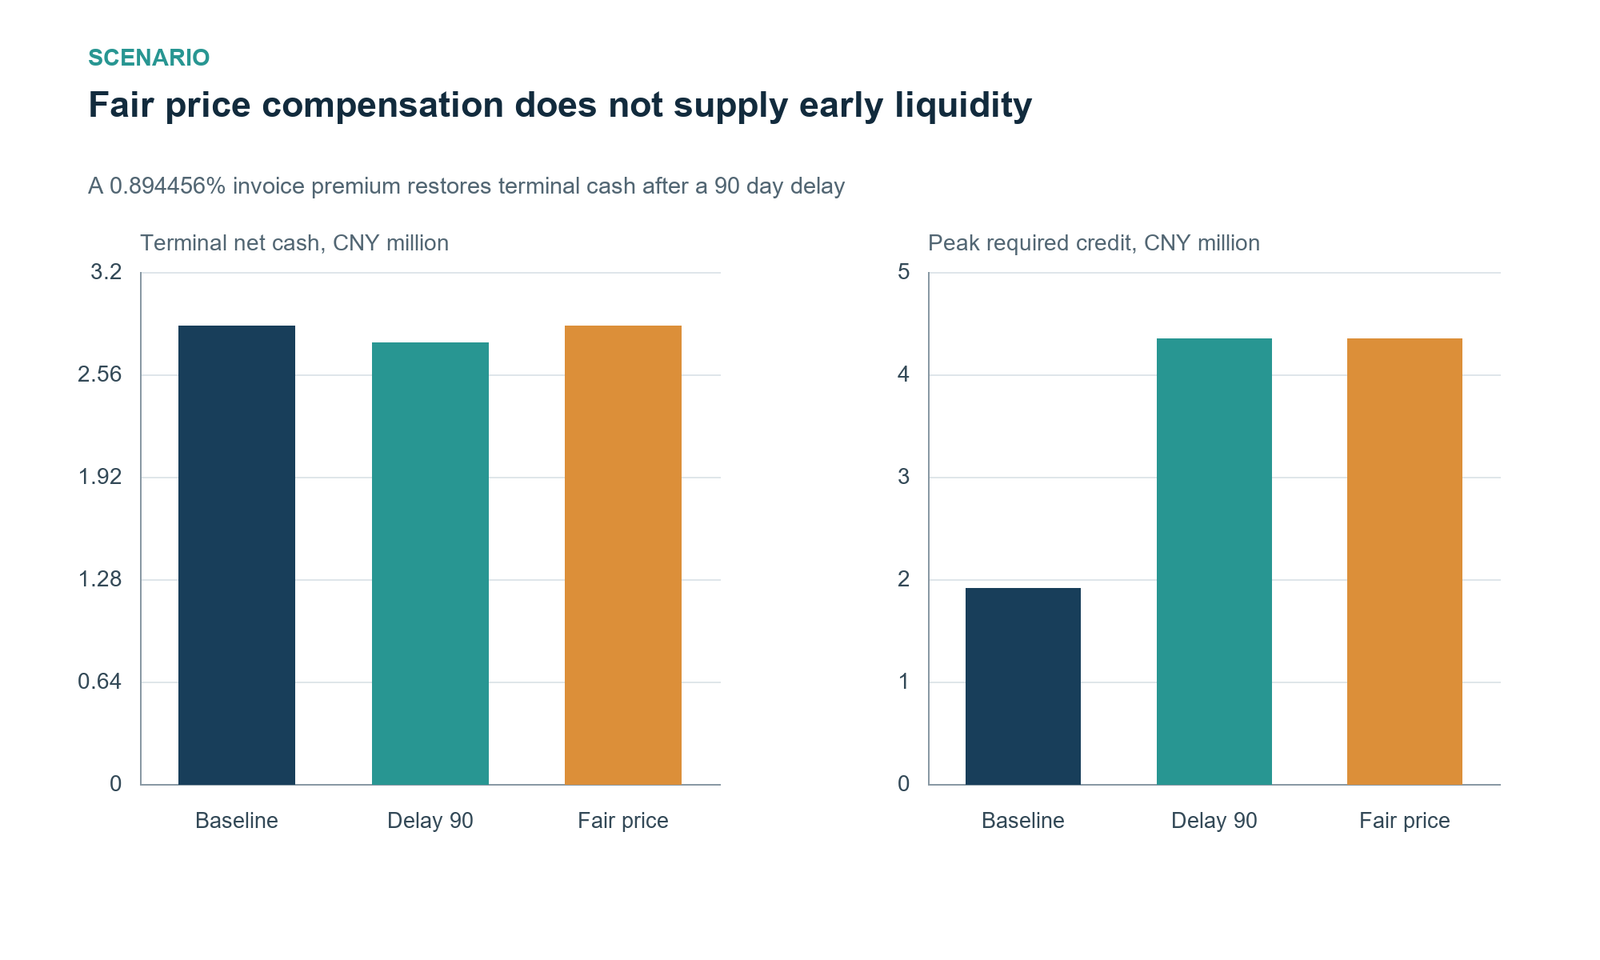
The model solves for a premium that equates delayed and baseline terminal net cash. With ninety additional collection days, a 0.894456% increase in invoice face restores terminal net cash to CNY 2.864055 million. The root calculation follows the full daily recurrence, including the way larger later receipts change subsequent interest. It is not simply the baseline interest increment divided by invoice value.
Peak required borrowing nevertheless remains CNY 4.348575 million. The first compensated receipt arrives after the earlier cash peak, so adding price to that receipt cannot finance production payments already due. Figure 12 places these two outputs side by side. Profit compensation and capacity relief answer different treasury questions, even in the same profitable order book.
Fair has a specific meaning here: equality of terminal net cash under the stated conventions. It does not denote a negotiated market premium, a continuous-equilibrium price, compensation for risk aversion or enforcement, or a guarantee that a buyer will pay. Buffer opportunity cost, taxes and receipt loss are absent from the central premium. Separate haircut sensitivities remain scenarios rather than actuarial prices.
An exporter with a binding line could therefore reject an apparently compensating price increase if it cannot bridge the earlier deficit. A deposit or enforceable advance at an earlier date can address that deficit differently. The calculation supports a contract-design distinction: place the receipt on the cash calendar before deciding whether its eventual amount compensates the exporter for carrying the claim.
Tail preferences change commitment decisions
At the central shortfall weight of 0.25 and maximum CNY 3 million line, the exhaustive grid selects CNY 1.85 million of available cash and a CNY 3 million commitment. All three stated delay paths are covered. The direct financing charge is CNY 149,292.14 for the full 620-day window, including buffer carry, commitment and expected drawn interest. It is neither an annual cost nor an observed exporter statistic.
Continue reading
Get the complete 30-page research note
The English PDF includes 16 scientific figures, 12 tables, source-vintage reconciliation, the full daily cash specification, both-direction currency gates, factoring, finite-grid treasury design, counterexamples and clickable primary references.
29 USD, instant PDF download, secure card payment.
Buy the full noteOne-time purchase. PDF only. Evidence cutoff: 24 October 2026. Conditional calculations are not an estimated causal effect or national funding gap.
Need this analysis for your organisation?
We prepare confidential briefings, executive talks and studies on countries, markets and policies, built on the same method as this article.
Request a briefingSupport independent analysis
Our studies are free to read and carry no advertising. If this one was useful, a small contribution helps us publish the next.
Support our workGo further: books by Global Strategy Files

Books from Global Strategy Files
Go further on this topic
The Tariff GambleHow America’s trade war is reshaping power, prices and prosperity.24.99 USD, see the book Future-Proofing AmericaEconomic challenges and the road to reform.20 USD, see the book
 Kill KennedyWhat the 2025 declassified files reveal about the machinery of American power.20 USD, see the book